Net Worth vs Liquid Net Worth: Which Number Matters and When
Net worth is everything you own minus what you owe. Liquid net worth counts only what you can spend. Here is how to calculate both and when each matters.
Published October 9, 2026
Say you add everything up and get a net worth of $310,000. Then you look at where it sits. $190,000 of it is home equity, $95,000 is a 401(k), and $25,000 is spread across checking, savings, and a brokerage account. The big number is real. It is also not much help when the transmission fails on a Tuesday.
That gap is the whole reason two numbers exist. This guide explains what each one measures, how to calculate them, and which questions each one can answer. It is not about how often to update them. If the monthly habit is your problem, that is a separate guide.
The Two Numbers, Plainly
Net worth is total assets minus total liabilities. Assets are things you own that have a value: cash, investments, retirement accounts, property, vehicles. Liabilities are what you owe: mortgage, car loans, credit cards, student loans.
Liquid net worth is the same subtraction with a narrower list of assets. You only count what you could convert to spendable cash quickly, without taking a big loss on the way. Checking, savings, and money market accounts qualify easily. Regular brokerage holdings usually do, with the caveat that selling at a bad moment costs you.
One thing worth knowing up front: there is no single official definition of liquid net worth. Lenders, advisors, and bank forms each draw the line slightly differently, mostly around retirement accounts. For your own purposes that is fine. What matters is that you pick a definition, write it down, and stay consistent, so that the number moves because your finances changed and not because you reclassified an account.
What Counts as Liquid and What Does Not
A useful test: can you have this money in your checking account within a few days, and roughly the amount you expect?
Usually liquid:
- Checking and savings accounts
- Money market and cash management accounts
- Taxable brokerage accounts (the value can swing, so some people haircut it)
- Cash you are certain to receive soon, such as a tax refund already filed
Usually not liquid:
- Your primary residence, even with plenty of equity
- Vehicles, which you need and which lose value
- Business equity you cannot easily sell
- Collectibles and anything where “value” is an estimate
- Money owed to you by friends or family
The gray area is retirement accounts. Many people can technically withdraw from a 401(k) or IRA early, but taxes and penalties can apply, and the rules depend on the account type and your circumstances. Rather than guess, many people track retirement as its own line and leave it out of the liquid figure. If you are considering actually tapping one, that is a question for a tax professional, not a spreadsheet.
How to Calculate Both in One Pass
You do not need two separate exercises. Build one list and tag it.
- List every account with a balance. Give each one a type: cash, investment, retirement, property, vehicle, other.
- Mark which types you count as liquid. Do this once and keep it.
- List every debt with its balance. Include the interest rate even though it does not change the total. It changes what you do next.
- Total everything for net worth. All assets minus all debts.
- Total the liquid assets only for liquid net worth. Then decide how to treat debts.
Step five is where people disagree, and it is worth thinking about. There are two reasonable approaches:
- Subtract all liabilities. This is the conservative version. If you owe $240,000 on a mortgage and have $30,000 liquid, your liquid net worth is deeply negative, which looks alarming but is mostly an artifact of the mortgage being a long, scheduled obligation.
- Subtract only short-term debts. Credit cards, personal loans, and medical bills that could come due soon. This version answers “what could I actually reach right now after clearing what is pressing?”
Neither is wrong. The second tends to be more useful for day-to-day decisions, and the first is closer to a strict reading of the term. Pick one, label it, and keep it.
When Each Number Is the Right One
Net worth and liquid net worth answer different questions, so reaching for the wrong one gives you the wrong comfort.
Use net worth when the question is long-term. Am I building wealth? Is my overall position better than a year ago? Net worth is the right lens for retirement planning, for judging whether debt payoff is paying off, and for seeing the effect of years of steady contributions. It moves slowly and rewards patience.
Use liquid net worth when the question is short-term. Could I cover a job gap? Can I put money down on something without selling investments at a bad time? Is my emergency fund actually an emergency fund? Here the big illiquid assets are not relevant, and counting them gives false reassurance.
Look at the ratio when you want a warning sign. If nearly all of your net worth is in a house and a retirement account, you may be wealthy on paper and fragile in practice. A simple check: divide liquid assets by your monthly spending to see how many months you could run without income. It does not require any benchmark from anyone else, and the answer is yours alone.
Here is a comparison that shows why both matter. Two people each have a net worth of $200,000. One holds $150,000 in home equity and $50,000 in a retirement account, with almost no cash. The other holds $60,000 in cash and brokerage accounts, $90,000 in retirement, and $50,000 in home equity. Same net worth. Very different ability to absorb a bad year.
Common Mistakes
Counting the asset and forgetting the debt. A car worth $18,000 with a $14,000 loan adds $4,000 to net worth, not $18,000.
Valuing your home at its dream price. Use a conservative estimate, and update it rarely. A house number that jumps around adds noise without telling you anything.
Changing the liquid list to feel better. If you move an account in or out of the liquid category because the number looks bad, you have stopped measuring and started decorating. Keep the definition fixed.
Treating a low liquid number as failure. Early in a career, or after a down payment, liquid net worth is often small. The point is to know it and have a direction, not to hit a figure someone else chose.
Tracking Both Without Doubling the Work
The practical trick is to log accounts with a type once, then let the totals be computed rather than retyped. That way a single set of balances produces both numbers.
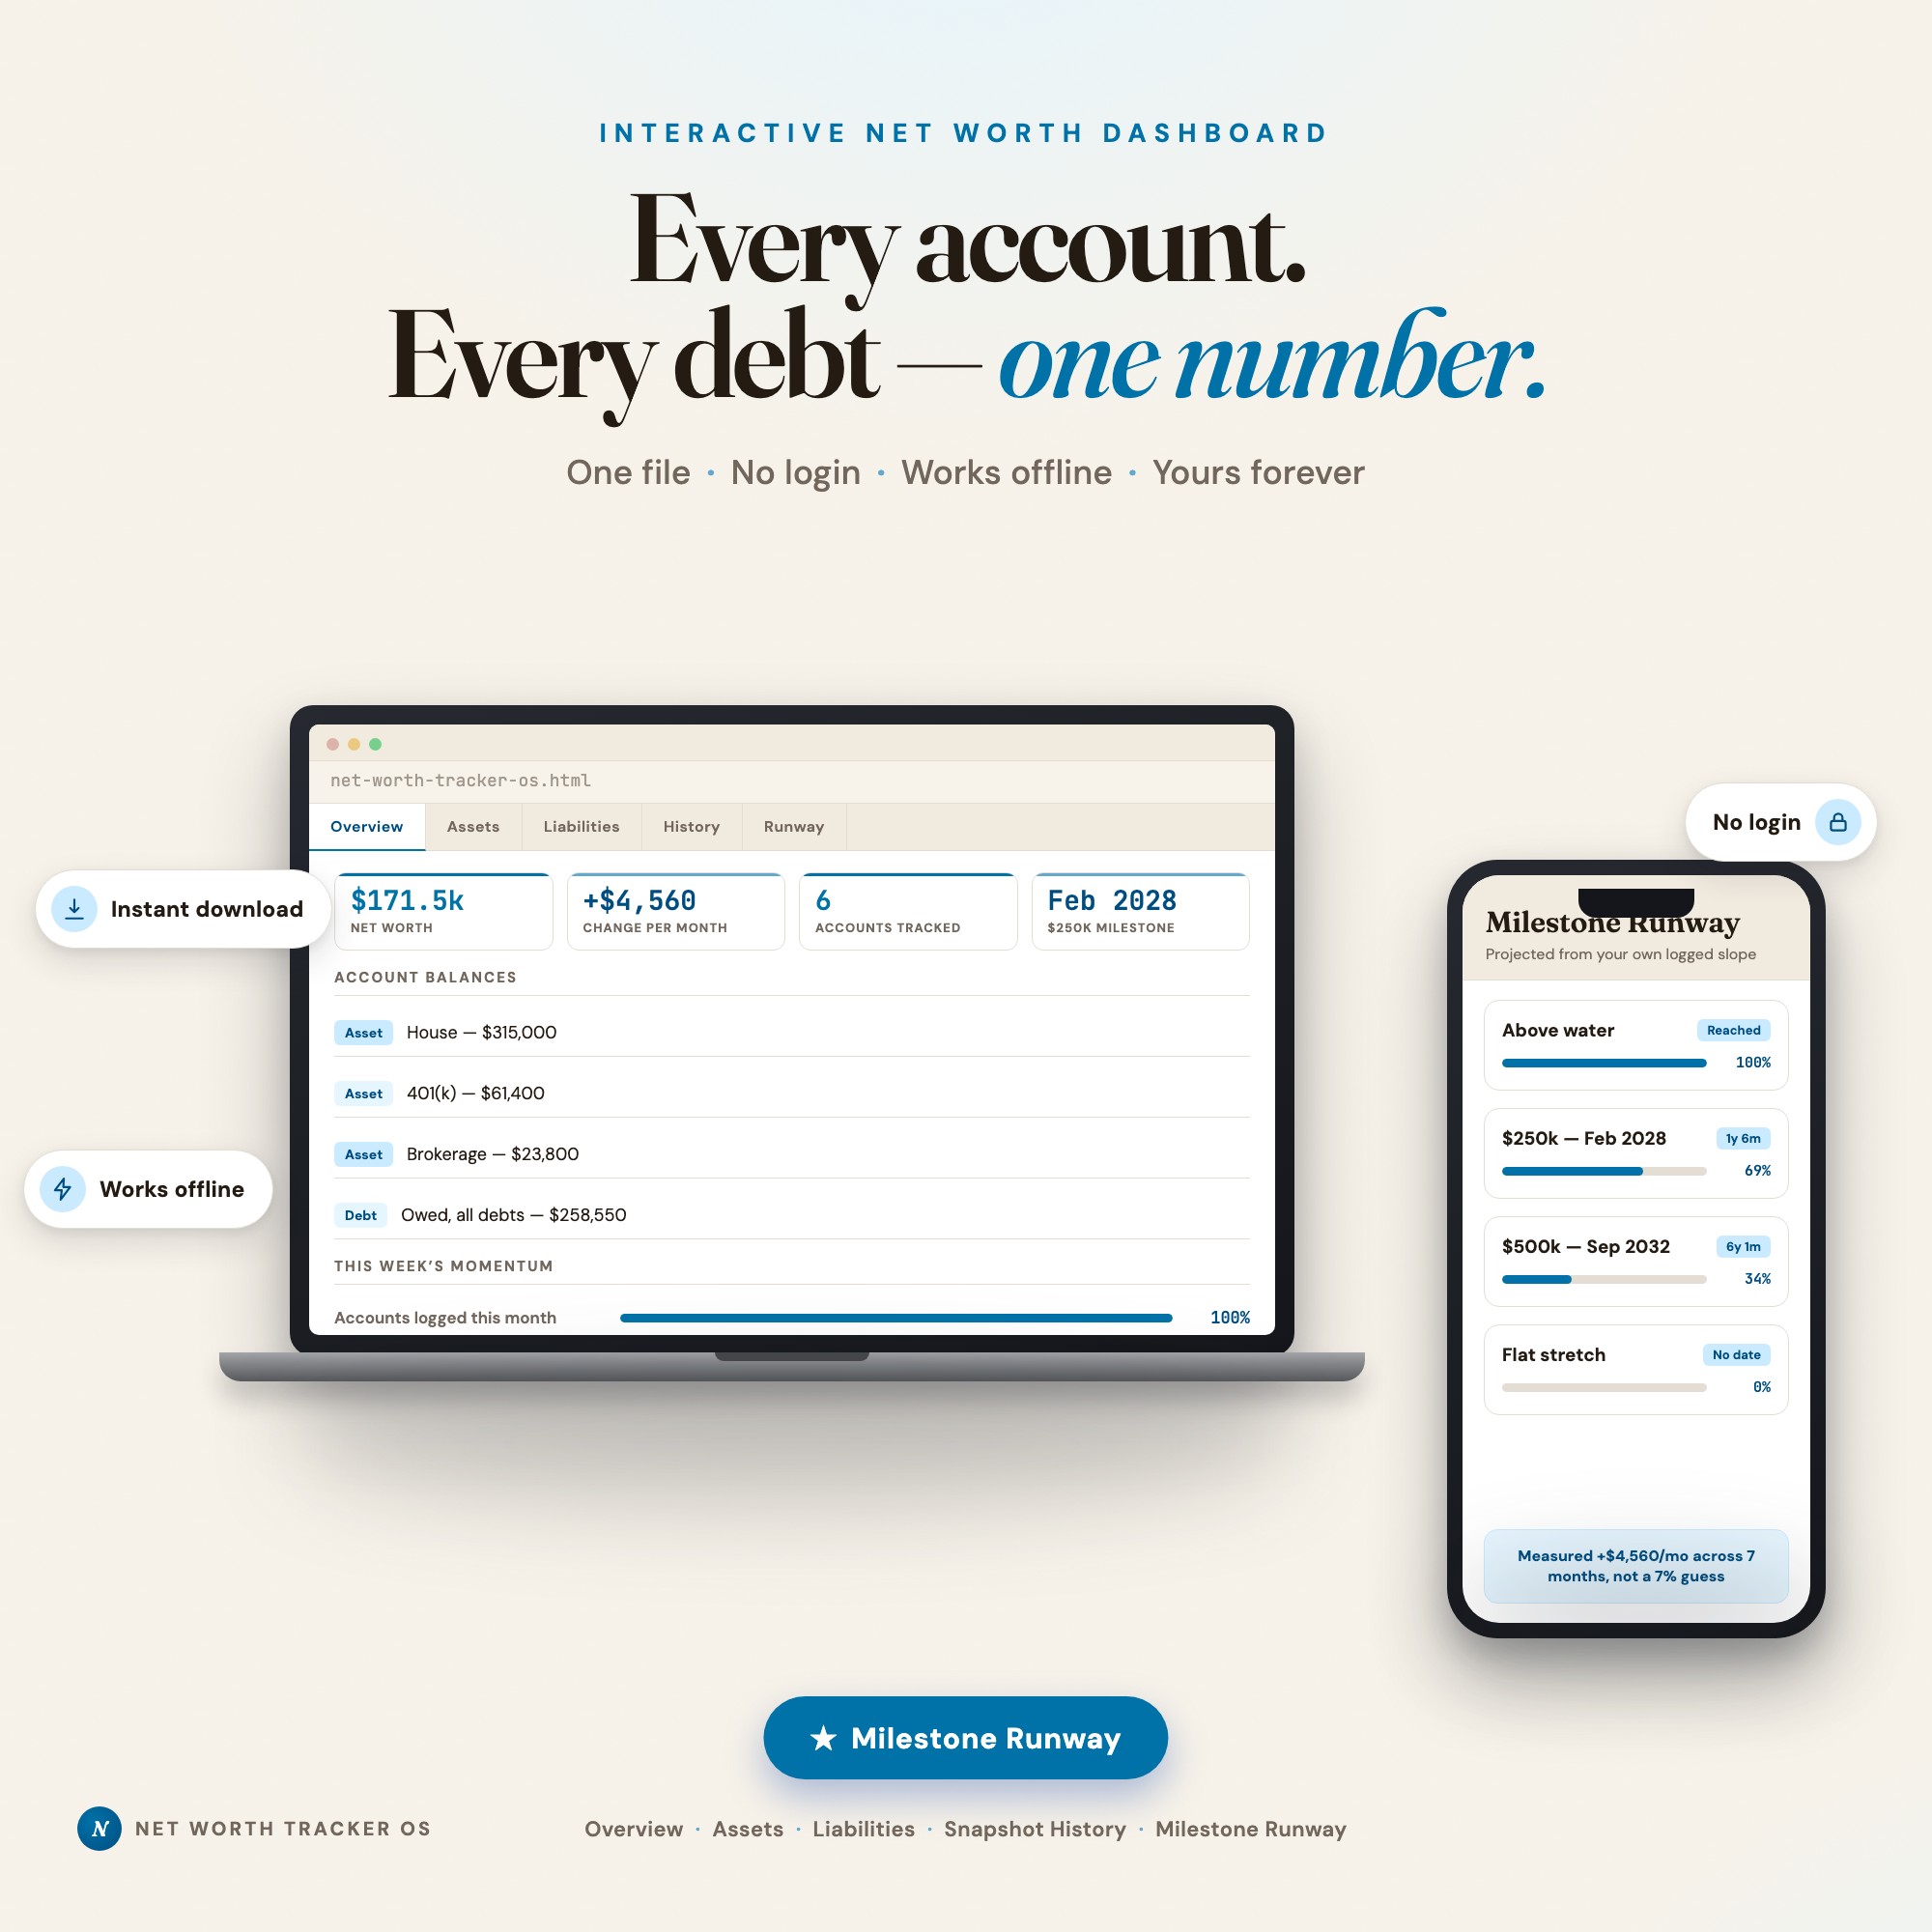
If you want a ready-made place to keep that, the Net Worth Tracker Dashboard has an Assets tab where each account carries a type, a Liabilities tab where each debt carries a balance, rate, and minimum payment, and a History tab where you log monthly snapshots. The Overview shows your total assets, total liabilities, and net worth, plus a chart of assets by category, so you can see how much of your total sits in each type. A Milestone Runway tab uses the months you have logged to project when you would cross the targets you set. It runs offline in your browser, and you can export a backup file.
It is not required, though. A spreadsheet with a type column and a subtotal for the liquid rows does the same job. The method matters more than the container.
A Short Starting Routine
If you do nothing else this week, do this:
- Write down every account and debt in one list.
- Tag each account as liquid or not, and note your rule for the gray areas.
- Calculate net worth and liquid net worth side by side.
- Write one sentence on what each number tells you. For example: “Net worth is healthy, liquid is thin, so cash is the priority.”
- Pick one action that follows from that sentence.
The point of having two numbers is to stop one flattering figure from hiding the other. Once you can see both, the next step is usually obvious.
Frequently asked questions
- What is the difference between net worth and liquid net worth?
- Net worth is everything you own minus everything you owe. Liquid net worth uses the same subtraction but only counts assets you could turn into cash quickly without a big loss, such as checking, savings, and brokerage accounts. Net worth tells you how much you have built. Liquid net worth tells you how much you could actually reach.
- Is there one official definition of liquid net worth?
- No. Banks, lenders, and advisors each draw the line a little differently, especially for retirement accounts. For your own tracking, the definition matters less than using the same one every month. Write down which accounts you count as liquid and do not change the list casually.
- Should my 401(k) count as liquid?
- Usually not. You can often get at retirement money before the standard withdrawal age, but taxes and penalties may apply, and the rules depend on the account type and your situation. Many people track retirement accounts as a separate line instead of folding them into either number. For specifics about your accounts, a tax professional is the right person to ask.
- Does my home count in net worth?
- Yes, at a realistic estimate, with the mortgage subtracted as a liability. It does not belong in liquid net worth, because you cannot spend part of your house. Selling takes time and costs money, and you still need somewhere to live.
- Which number should I focus on?
- Watch both, for different questions. Net worth answers whether you are building wealth over years. Liquid net worth answers whether you can handle a job loss, a repair, or a large purchase this year. If you can only watch one while you have a gap in your cash cushion, watch the liquid one.
- What does the Net Worth Tracker Dashboard cost?
- One-time purchase of $24 on Etsy. No subscription and no login. It runs as a single file in your browser and your figures stay on your own device.
Ready-made dashboards
Skip setup — grab an interactive dashboard built for this exact workflow.
ListingResearchOS Shop
All dashboards — one-time purchase, yours forever
Single HTML files. No subscriptions. No login. Works offline in any browser.
Browse all dashboards →